How to Use a Mortgage Calculator in Estonia: A Guide for First-Time Buyers

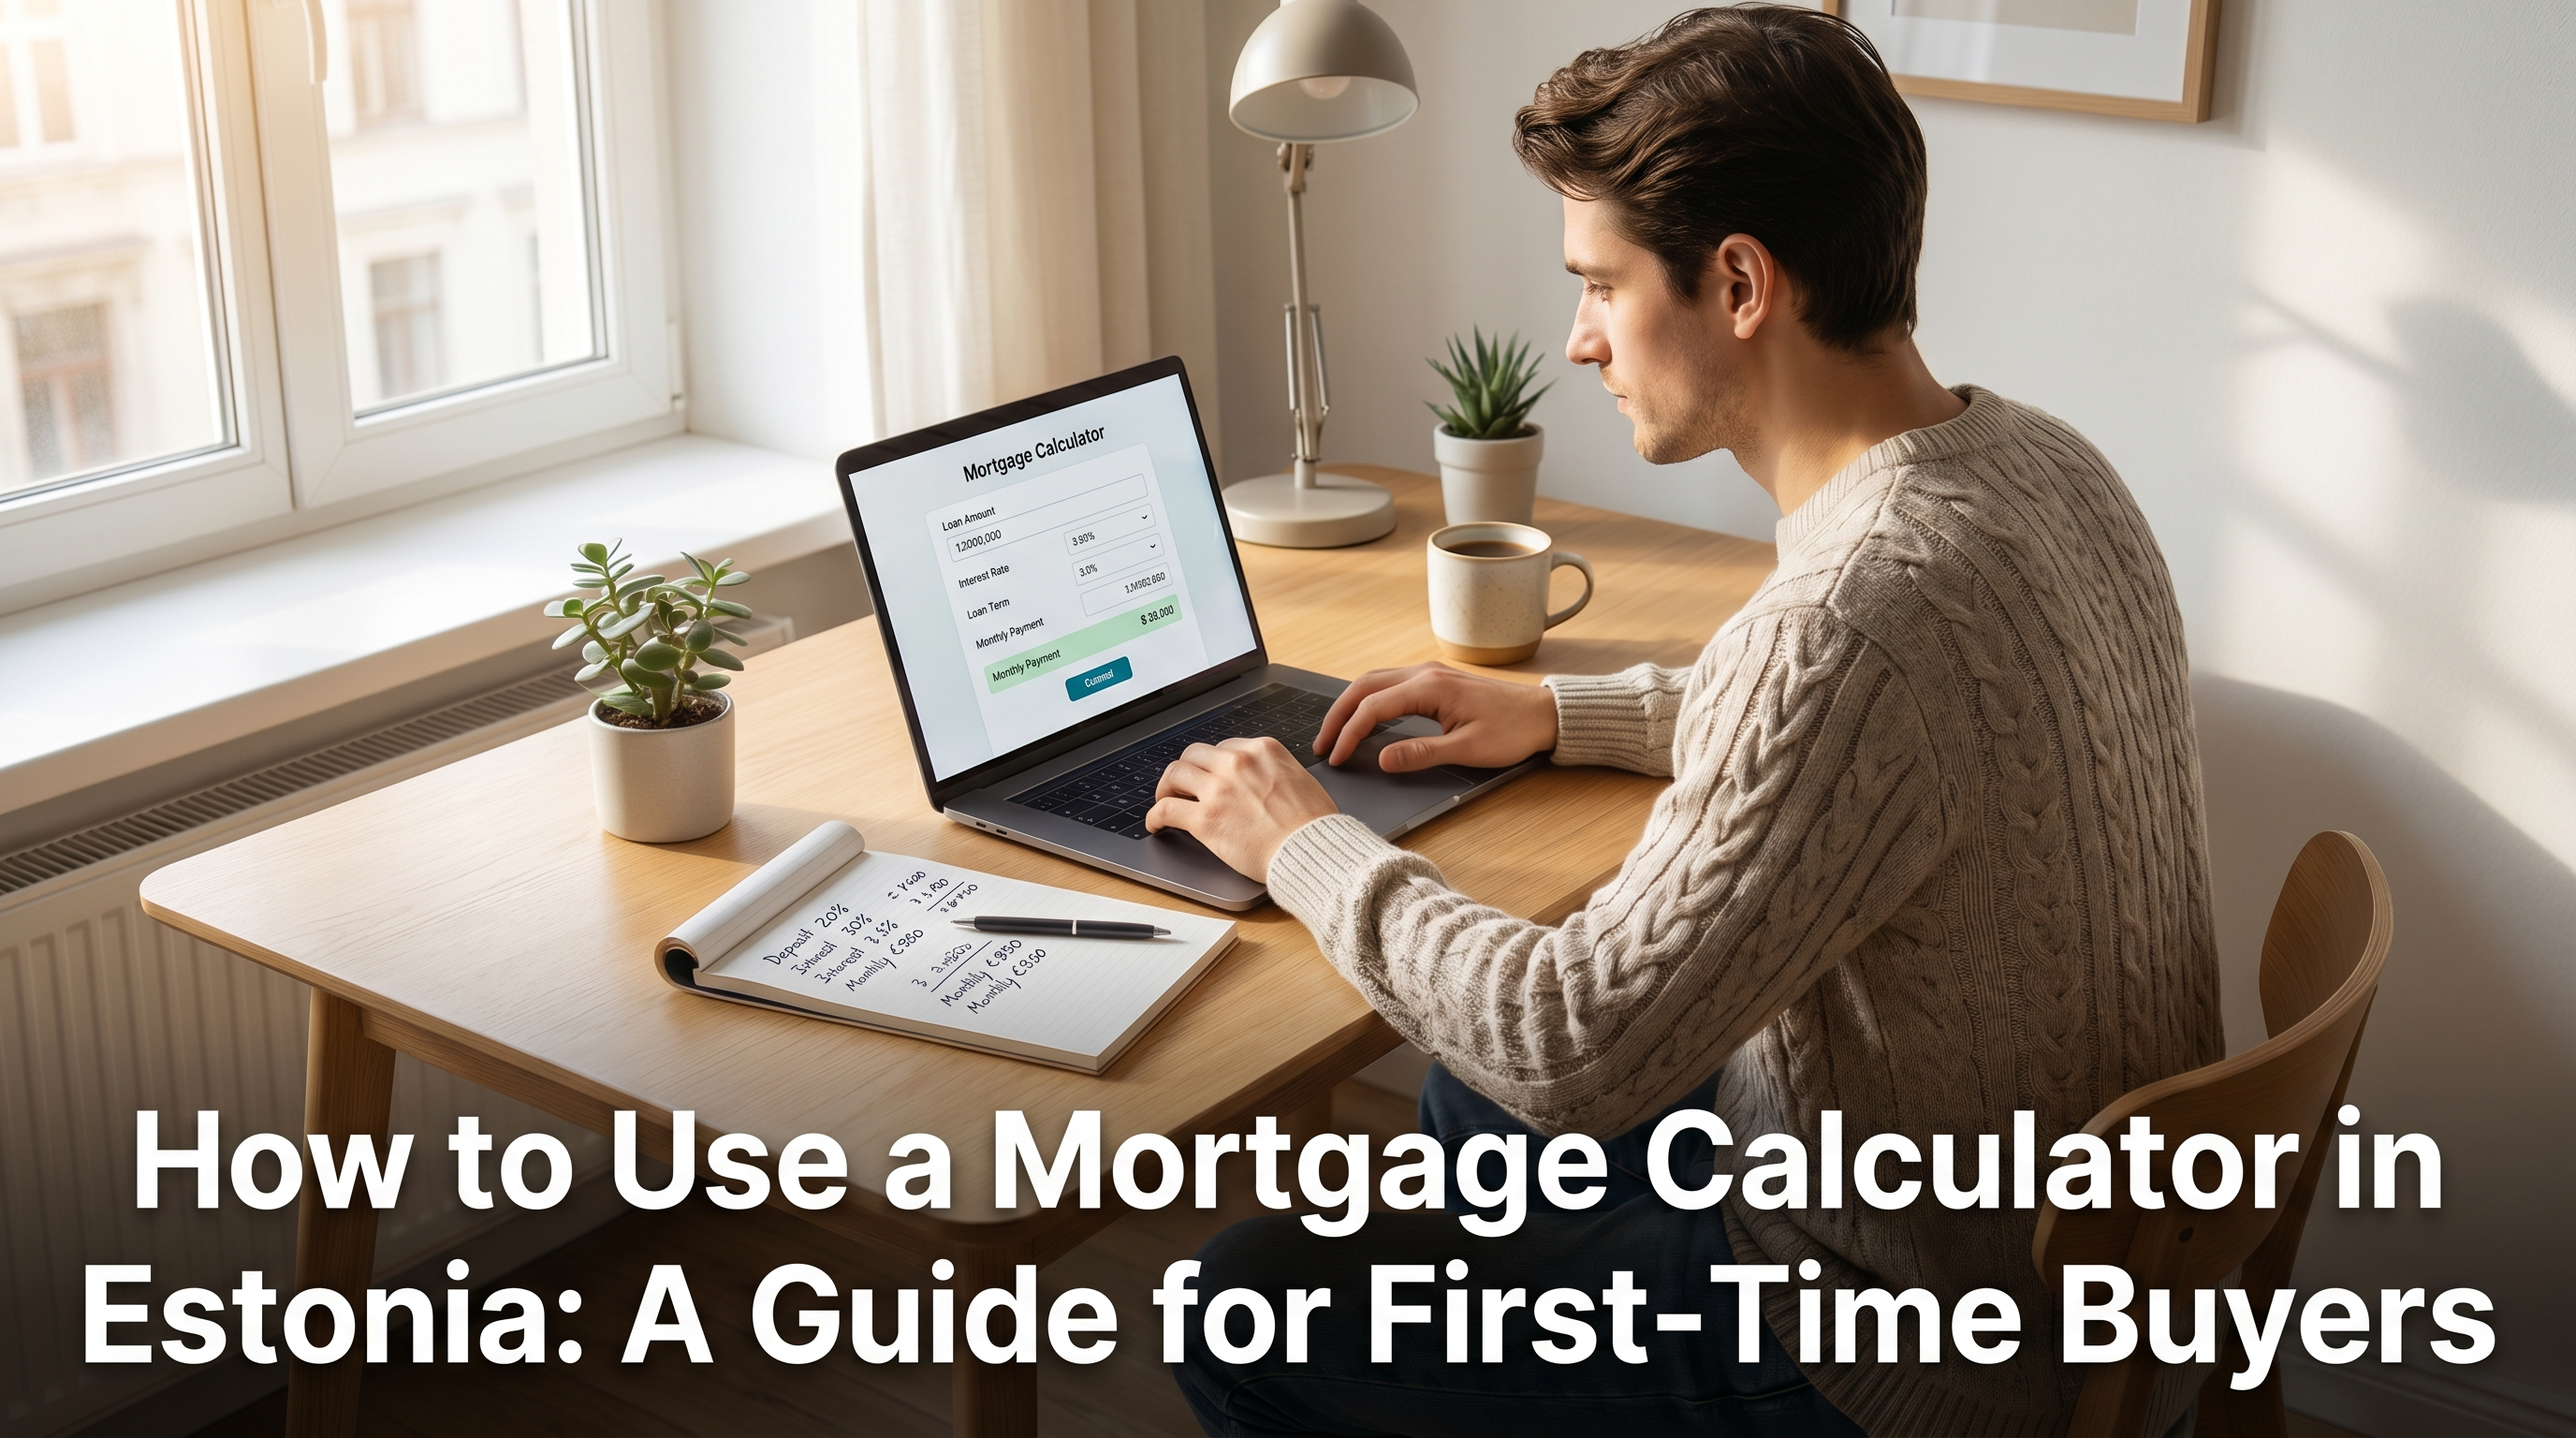
A mortgage calculator is one of the most useful tools available to any property buyer — but only if you know how to use it properly.
Too many first-time buyers plug in a purchase price and a vague interest rate, look at the monthly payment, and assume they have done their planning. Real financial planning for an Estonian property purchase is more nuanced than that. Here is how to use a mortgage calculator in a way that gives you genuinely useful information.
What a Mortgage Calculator Actually Does
A mortgage calculator takes four inputs — loan amount, interest rate, loan term, and sometimes the deposit amount — and calculates the monthly repayment. What it does not automatically show you is the total cost of ownership, which includes land tax, apartment association fees, insurance, maintenance, and utility costs — all of which sit on top of the mortgage payment.
Step One: Set the Right Loan Amount
Start with the purchase price. Subtract your deposit. The result is your loan amount. In Estonia, most banks require a minimum deposit of 15-20% for resident buyers and 30-40% for non-resident buyers.
If you are stretching to the maximum loan-to-value, be realistic about the buffer you are leaving for purchase costs, first-year expenses, and unexpected costs in the early months of ownership. Our mortgage calculator allows you to adjust the deposit percentage to see how different deposit sizes affect your monthly payment and total interest paid.
Step Two: Use a Realistic Interest Rate and Term
Estonian mortgage rates are linked to Euribor plus a bank margin. When using a calculator for planning purposes, use the current rate you have been quoted or research the current typical range. It is also worth running the calculator at a rate 1-2 percentage points higher as a stress test.
For the loan term, run the calculator at both 20 and 30 years and compare the monthly payments and total interest. For most first-time buyers, the 25-30 year range provides the right balance between affordability and not over-paying on interest.
Step Three: Add the Non-Mortgage Costs
Once you have a monthly repayment figure, add your realistic monthly estimates for:
• Apartment association fee: typically €30-150 per month depending on building and location
• Home insurance: €15-35 per month
• Land tax: a small monthly equivalent, typically under €20 for most urban apartments
• Maintenance reserve: budget at least €50-100 per month for ongoing upkeep
The total of these figures is your true monthly cost of ownership — and this is the number you need to be able to afford comfortably, not just the mortgage repayment alone.
Step Four: Compare Against Renting
Once you have the full monthly ownership cost, compare it honestly against what you would pay in rent for a comparable property. In many Estonian markets, the total monthly cost of ownership is not dramatically higher than market rent — and you are building equity rather than paying someone else's mortgage.
Visit our mortgage calculator to run your own numbers. Browse our properties page to see what is available, and our FAQ page covers common mortgage questions. If the mortgage route is not yet accessible, our rent-to-own programme is worth exploring. Get in touch with the team to talk through your numbers before you start viewing.

Comments